 how-to
How to Handle Multiple Offers on My Home
Table of Contents
- What Multiple Offers Really Mean for Your Sale
- How to Compare Home Purchase Offers Beyond the Price
- What Is an Escalation Clause in Real Estate and When to Use One
- Running a Highest and Best Offer Strategy
- Negotiating Counteroffers When the Numbers Are Close
- Common Mistakes Sellers Make With Multiple Offers
- Frequently Asked Questions
Last Updated: October 1, 2026
What Multiple Offers Really Mean for Your Sale
Getting multiple offers on your home means buyers are competing for it. That competition is good news, but it also puts a decision in front of you: pick one, or ask everyone to improve. Knowing how to handle multiple offers on my home comes down to reading each offer as a package, not just a price. In Ukiah, CA, where the market moves at its own pace, that skill protects your equity.
This guide from Nathan Fine walks through how to compare offers, when to use an escalation clause, and how to run a highest and best round without scaring buyers off. Nathan Fine is a third-generation agent who works with sellers across Sonoma, Mendocino, and Lake Counties.
A real estate agent and homeowner sitting at a dining table reviewing several printed offer documents, with a laptop open and a pen in hand, warm natural light from a window
A common mistake is assuming the biggest number wins. It rarely does. The strongest offer is the one most likely to close on time at the price the buyer promised.
How to Compare Home Purchase Offers Beyond the Price
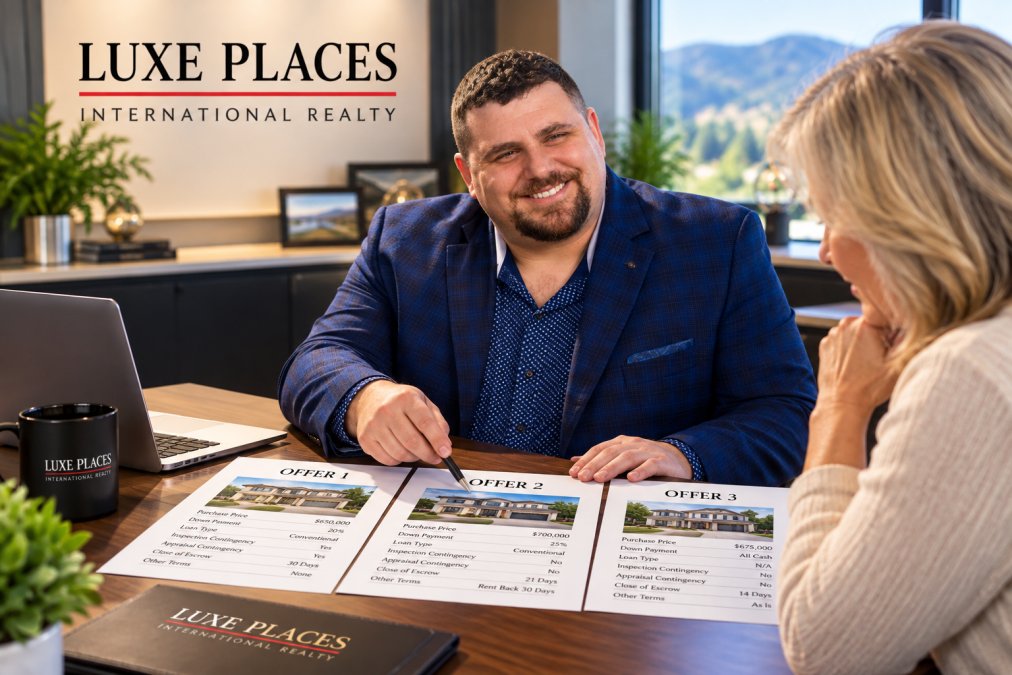
To compare home purchase offers, line them up side by side and score four things: financing, contingencies, timeline, and flexibility. The highest price means nothing if the buyer's loan falls apart in week three.
Start with a simple scoring sheet. Rate each offer from 1 to 5 on the factors below, then add the totals.
Factor | What to Check | Why It Matters |
|---|---|---|
Financing type | Cash, conventional, FHA, VA | Cash closes fastest; some loans add appraisal risk |
Down payment | Size of the deposit | Bigger deposits signal a committed buyer |
Contingencies | Inspection, appraisal, loan | Fewer contingencies mean less risk to you |
Timeline | Close date and rent-back | Matches your moving plans |
Flexibility | Willingness to adjust terms | Room to negotiate if issues come up |
A buyer with 20 percent down and a conventional loan is usually safer than one stretching for a low down payment. That is not a knock on the buyer. It is risk math.
Financing Type and Down Payment Strength
Financing strength tells you how likely the deal is to close. Cash offers skip the lender entirely. Conventional loans with a solid down payment are next. Government-backed loans can be great for buyers but often come with stricter appraisal rules that can slow a sale.
Ask your agent to check the buyer's pre-approval letter, not just a pre-qualification. A pre-approval means a lender already reviewed income and credit.
Contingencies, Timelines, and Buyer Flexibility
Contingencies are exit doors for the buyer. An inspection contingency lets them walk or renegotiate if the home has problems. That is normal and healthy. But a stack of contingencies with long deadlines adds risk for you.
Look at the close date too. A fast close is not always better. If you need time to move, a buyer who offers a rent-back period can be worth more than a slightly higher price.
What Is an Escalation Clause in Real Estate and When to Use One
An escalation clause in real estate is a contract term that automatically raises a buyer's offer when a competing offer comes in. The buyer sets a cap, and the price climbs in set increments until it hits that ceiling.
Here is how it works in plain terms:
- Buyer offers a base price, say their starting number
- The clause says their offer goes up by a fixed amount each time another offer beats it
- The buyer names a maximum they will not exceed
- You must show proof of the competing offer for the clause to trigger
Escalation clauses work best when you have two or three serious buyers and you want the price to climb without another full round. They fall short when a buyer sets a low cap or when the proof requirement gets messy.
Running a Highest and Best Offer Strategy
A highest and best offer strategy means you ask every buyer to submit their final, strongest terms by a set deadline. It is the cleanest way to handle multiple offers on my home when the first round comes in close.
Set a deadline, usually 24 to 48 hours out. Tell every buyer the same thing: this is your chance to put your best foot forward. No one gets a second bite after the deadline passes.
A few rules keep this fair and effective:
- Give all buyers the same deadline and the same information
- Ask for final price plus any changes to contingencies or timeline
- Do not reveal one buyer's terms to another
- Review everything at once after the deadline
The highest and best round tends to surface the buyer who truly wants the home. It also protects you from endless back-and-forth.
Consumer Financial Protection Bureau guide to closing on a home
Negotiating Counteroffers When the Numbers Are Close
When two offers land within a small gap, a counteroffer lets you push for better terms without losing the buyer. The trick is knowing what to ask for.
Price is the obvious lever, but it is not the only one. Try these instead when the buyer is already near their limit:
- Ask for a shorter inspection window
- Request a larger earnest money deposit
- Reduce or remove the appraisal contingency if the buyer can cover a gap
- Adjust the close date to fit your move
Pick the lever that matters most to you. If you need speed, push the timeline. If you need certainty, push the deposit and financing.
A counteroffer is a conversation, not a demand. Buyers who feel respected tend to say yes. Buyers who feel squeezed walk away.
Common Mistakes Sellers Make With Multiple Offers
The biggest mistake sellers make is chasing the top number and ignoring the risk behind it. A high offer with shaky financing can collapse weeks later, and by then your best backup buyer is gone.
Other missteps show up again and again:
- Letting buyers bid against each other in the open, which can feel unfair and scare people off
- Ignoring the backup offer and releasing a buyer who could still close
- Skipping proof on escalation clauses
- Rushing the decision before all offers are in
- Failing to check the buyer's actual pre-approval
For sellers in Ukiah and across Lake and Mendocino Counties, patience pays. A clean offer at a fair price often beats a flashy offer that never closes.
If you are weighing a sale and want a local agent who knows these markets, working with someone dedicated to problem-solving makes the process smoother.
National Association of Realtors guidance on offers and negotiation
Frequently Asked Questions
Do I have to accept the highest offer when selling my home in California?
No. In California, you are not legally required to accept the highest offer. Price is only one factor. A lower offer with a large down payment, no appraisal contingency, or a flexible closing date can net you more money and less stress than a higher offer that may fall through. Review every term, not just the number, and choose the offer that best matches your timeline and risk tolerance.
Can I disclose the terms of competing offers to other buyers?
You can share general information, such as the number of offers or that you have received an offer above asking, but you should not reveal another buyer's confidential terms, like their exact price or personal financial details. Your agent can tell other buyers that they are in a multiple-offer situation and invite their highest and best. Always let your agent manage communication to avoid fair-housing or privacy issues.
Should I accept an all-cash offer over a financed offer with a higher price?
It depends on the gap. An all-cash offer removes appraisal and loan contingencies, so it often closes faster and with less risk. A financed offer with a higher price can still win if the buyer is well-qualified, the down payment is substantial, and the appraisal gap is covered. Compare the net proceeds after any concessions and the likelihood of closing. A cash offer that is 5% lower may be safer than a financed offer that is 10% higher but carries appraisal risk.
How does a contingency affect the strength of an offer?
Contingencies are conditions that must be met for the sale to close. Common ones include inspection, appraisal, and financing. The more contingencies, the more ways the deal can fall apart. An offer with few or no contingencies is stronger because it gives you more certainty. If a buyer asks for a home inspection contingency, you can negotiate a shorter inspection window or ask for a higher deposit to offset the risk.
Handling multiple offers is a test of judgment, not just math. The right choice balances price, risk, and timing. Nathan Fine - Realtor brings a third-generation, problem-solving approach to sellers across Sonoma, Mendocino, and Lake Counties, with tireless advocacy, informed guidance, and creative solutions for every deal. Get started with Nathan Fine - Realtor and turn your multiple offers into a clean, confident sale.